High-Risk Merchant Accounts: Approvals & Chargeback Solutions
High-risk merchant accounts demand providers who combine fast approvals with transparent pricing and proactive chargeback controls. Charge.com delivers no setup fees, no cancellation fees, and no long-term contracts, with rates as low as 0.25 percent. Free payment processing software and card readers support online, in-person, phone, mail, and fax transactions, backed by 24/7/365 customer support.
Key Takeaways
- Charge.com approves high-risk merchant accounts within 48 hours with no setup or cancellation fees.
- Our rates start as low as 0.25%, making credit card processing affordable for restricted businesses.
- We accommodate merchants in CBD, vape, firearms, adult, crypto, telehealth, and subscription industries seamlessly.
- Charge.com’s 24/7/365 customer support helps high-risk businesses implement effective chargeback mitigation strategies immediately.
What Makes a Merchant Account High-Risk?
Industry type, business model, chargeback history, and regulatory factors determine high-risk classification, not any fault of the business owner. A high-risk merchant account designation reflects statistical risk patterns tied to a sector or sales method, according to Technology Advice’s Best High Risk Merchant Account Providers 2026 report. Owners often assume the label signals poor business practices. That assumption is false.
The consequences, however, are real. Businesses carrying this classification commonly encounter stricter underwriting reviews, elevated processing fees, and a higher rate of account declines, per the same report. Those obstacles make choosing the right processing partner a critical decision rather than a routine one.
Why does chargeback history matter so much?
Chargeback history ranks among the core factors behind high-risk status. A pattern of disputed transactions signals elevated future risk to underwriters, regardless of the circumstances behind individual cases. Reducing dispute frequency through strong chargeback mitigation practices directly affects how a processor evaluates an account.
Does a high-risk label mean a business cannot get approved?
No. Classification affects terms and scrutiny, not eligibility. Charge.com provides merchant credit card processing services built to give businesses an affordable, convenient way to accept credit cards. The company accommodates merchants across varying credit backgrounds, extending accessibility and support to all legal businesses.
Common high-risk triggers include:
- Industry type (certain goods or services carry inherent dispute risk)
- Business model (subscription billing, high-ticket sales, card-not-present transactions)
- Chargeback history (elevated dispute rates from prior processing)
- Regulatory requirements (industries subject to added compliance oversight)
Is Instant Approval Really Possible?
True instant approval for a high-risk merchant account does not exist. Underwriting and compliance checks take real time, and no legitimate provider can skip that step. Any pitch promising guaranteed same-day approval deserves skepticism.
Why does the skepticism matter? Instant approval payment processing claims often gloss over the risk review every acquiring bank must perform. That review covers bank statements, processing history, and industry-specific risk factors, including chargeback rates. Chargeback mitigation policies, fraud screening, and regulatory checks all require manual evaluation before a bank signs off. Skipping those steps would expose the bank itself to unacceptable liability.
Fast approval is still realistic, though, even without a true instant process.
What actually speeds up high-risk merchant account approval?
Preparation shortens the wait more than anything else. Applicants who submit complete documentation, such as EIN records, Articles of Incorporation, and recent processing statements, avoid the delays caused by back-and-forth requests. Clean processing history and a provider with direct high-risk experience also reduce the number of underwriting rounds needed before funds can move.
Should every “instant” claim be trusted?
No. Phrasing that promises instant or guaranteed approval signals a provider glossing over underwriting rather than one that has streamlined it. A dependable High-Risk Merchant Account Guide separates honest timeline expectations from marketing shortcuts.
Charge.com pairs that honesty with cost transparency: no setup fees, no cancellation fees, no long-term contracts, and rates as low as 0.25%. Reliability, not speed claims, is what separates a trustworthy processor from the rest.
What Does the Application Process Involve?
A merchant account functions as a specialized bank account that lets a business accept credit card payments. Three parties enter into this arrangement: a retailer, a merchant bank, and a payment processor, each playing a distinct role in settling transactions. Approval for a high-risk merchant account follows a similar structure, though documentation requirements run deeper and review takes longer.
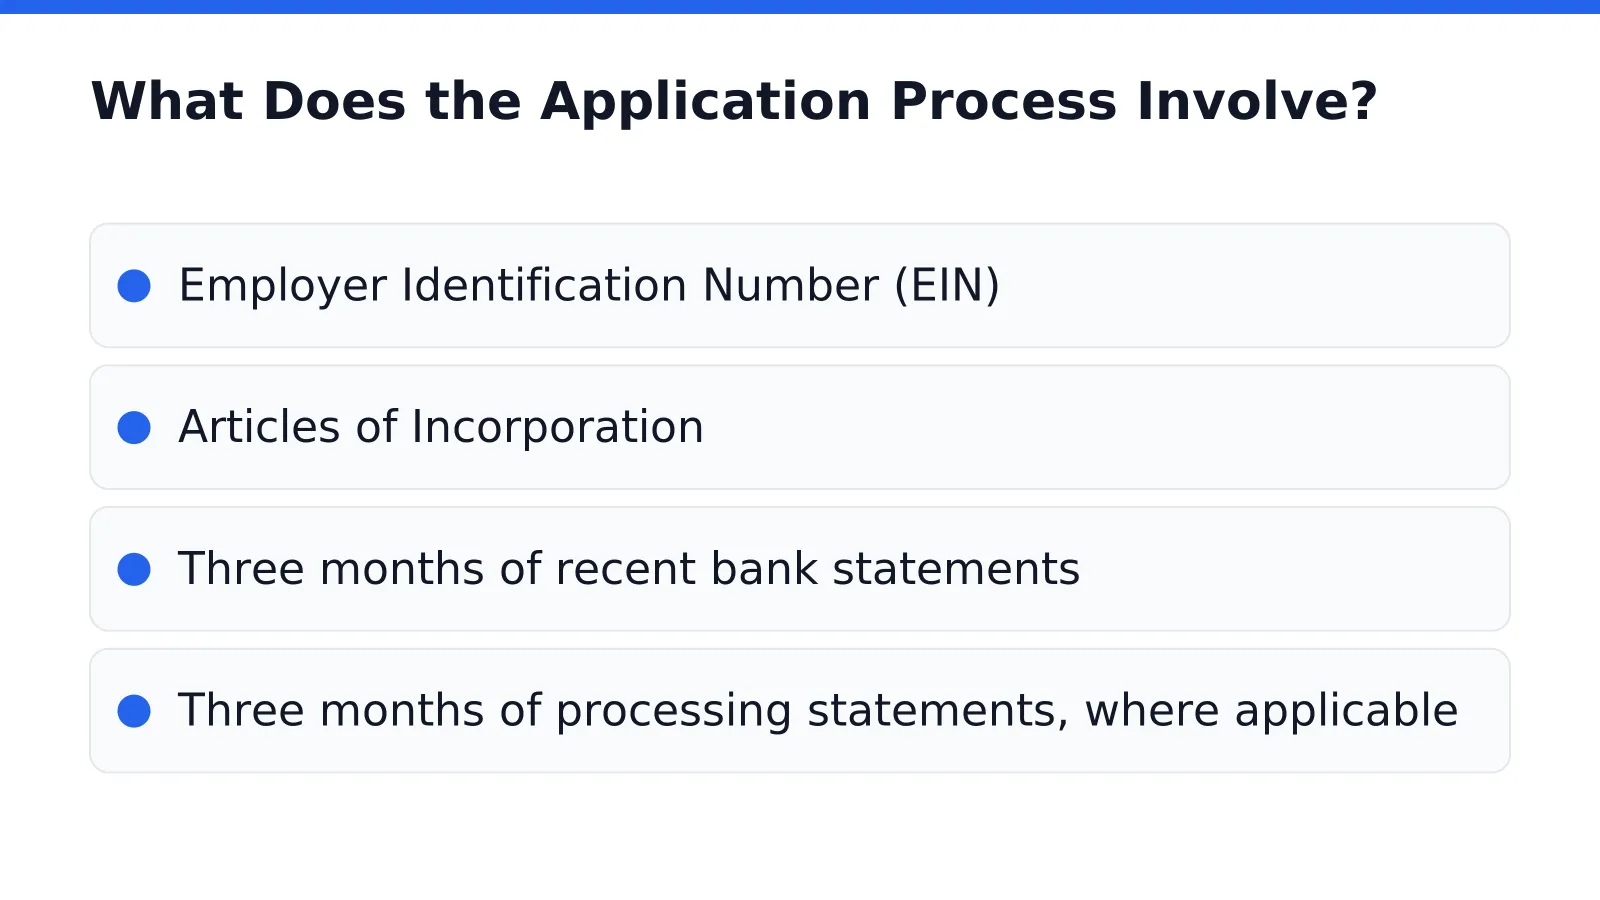
Applicants typically submit a defined set of records before underwriting begins:
- Employer Identification Number (EIN)
- Articles of Incorporation
- Three months of recent bank statements
- Three months of processing statements, where applicable
What Do Underwriters Look For?
Underwriters examine three core factors: the business model itself, monthly transaction volume, and the chargeback ratio. Businesses with cleaner chargeback histories and predictable volume patterns move through review with fewer complications. These three factors determine both approval odds and the pricing structure attached to the account.
Does Approval Happen Instantly?
No approval process is truly instantaneous, since underwriting review requires time to verify documentation and risk exposure. Marketing claims of instant approval payment processing describe expedited timelines, not an absence of review. A well-prepared application, with accurate paperwork and transparent chargeback mitigation practices already in place, still moves faster than an incomplete one.
Once approved, merchants receive account credentials and connect their payment gateway, whether through in-person terminals, online checkout, phone, mail, or fax. This multichannel flexibility lets retail operators and e-commerce merchants manage transactions from a single account regardless of how the customer chooses to pay.
How Can Merchants Reduce Chargeback Risk?
Merchants lower dispute rates by combining the right processing partner with disciplined transaction practices. Choosing a provider without strong support or outdated equipment leaves gaps that disputes slip through, costing merchants revenue and time on every contested sale. A high-risk merchant account paired with reliable tools and responsive service closes many of those gaps before a dispute ever reaches a bank.
Technology Advice’s 2026 review of high risk merchant account providers evaluated vendors on pricing, features, reliability, and approval flexibility. That framework matters for merchants weighing chargeback mitigation strategies. A provider strong in one area but weak in another often leaves exposure unaddressed. Reliability and approval flexibility, in particular, determine whether a merchant can keep processing without sudden freezes that trigger customer disputes.
What tools actually reduce dispute volume?
Free payment processing software and card readers for computers and mobile devices support accurate transaction capture at the point of sale. Accurate capture reduces the errors and mismatched records that often fuel disputes in the first place.
Does support availability affect chargeback outcomes?
Yes. Round-the-clock customer support, available 24/7/365, gives merchants continuous access to help when a transaction is disputed. Quick response to a flagged charge improves the odds of resolving it before it escalates.
Merchants processing large transaction volumes face compounded risk, since more transactions mean more opportunities for error or fraud. High-volume processing solutions, built to handle heavy transaction loads securely and efficiently, address that exposure directly, supporting consistent performance as sales scale.
What Should Merchants Do Next?
Merchants ready to accept credit cards online start by comparing providers on cost, support, and track record. Six consecutive years of being rated the #1 merchant account provider separate Charge.com from newer or untested competitors. No setup fees, no cancellation fees, and no long-term contracts remove the financial traps that lock businesses into poor service. Rates as low as 0.25 percent give small operators room to price competitively without sacrificing margin.
Who Should Apply for a Merchant Account?
Any small business or e-commerce operation planning to accept credit card payments online needs an internet merchant account. This applies equally to brick-and-mortar retailers expanding online and digital-only sellers launching their first storefront.
Is Approval Realistic for Businesses With Credit Challenges?
Approval remains realistic even for merchants with uneven credit history. More than 25 years of operating experience lets Charge.com accommodate businesses across varying credit backgrounds, rather than limiting service to applicants with flawless financial records.
Securing a merchant account is achievable for virtually all small businesses, provided they choose the right provider. The next step is straightforward:
- Review pricing structures and contract terms before committing.
- Confirm the provider supports instant approval payment processing workflows suited to the business model.
- Consult a High-Risk Merchant Account Guide when operating in a restricted or high-chargeback category.
- Request a direct quote to compare real costs against current processing fees.
FAQ
Does a high-risk classification mean a business did something wrong?
No. Industry type, business model, chargeback history, and regulatory factors drive the classification, not poor business practices. Charge.com accommodates merchants across varying credit backgrounds and supports all legal businesses regardless of risk category.
How fast does Charge.com approve high-risk merchant accounts?
Charge.com approves high-risk merchant accounts within 48 hours, with no setup fees or cancellation fees. True instant approval doesn’t exist because underwriting and compliance checks always require real time to complete.
What can a high-risk business do to improve approval odds and lower fees?
Reducing chargeback frequency through strong mitigation practices directly improves how processors evaluate an account. Charge.com’s 24/7/365 support helps merchants implement effective chargeback mitigation strategies immediately, alongside rates as low as 0.25%.
Conclusion
In closing, securing a high-risk merchant account requires selecting a processing partner equipped with the infrastructure, expertise, and support systems to address chargeback exposure at every transaction stage. Charge.com delivers that foundation through competitive pricing, free equipment, round-the-clock support, and approval flexibility across varying credit profiles. Merchants who combine account selection with disciplined transaction practices and responsive dispute management establish the operational framework necessary to process payments reliably and sustain profitability in high-risk categories.